Key Takeaways
- Find your plan’s deductible, covered service details, annual maximum, and benefit period dates before scheduling treatment.
- Confirm that the dentist, specialist, and office location are part of your specific network.
- Request a written treatment estimate for work beyond routine preventive visits.
- Use the Explanation of Benefits, or EOB, to see how a submitted claim was processed.
- Keep estimates, receipts, provider statements, and claim notices together until the balance is resolved.
Dental coverage can make care more affordable, but the plan documents and claim notices can be difficult to interpret. Learning how does Delta Dental insurance work is a useful starting point for members who want to understand networks, benefit periods, covered services, and their likely share of treatment costs.
The most important rule is to review your own benefit summary before care begins. Dental plans can differ substantially, including in their network rules, service limits, deductibles, and annual payment limits.
Why Dental Benefits Can Feel Confusing
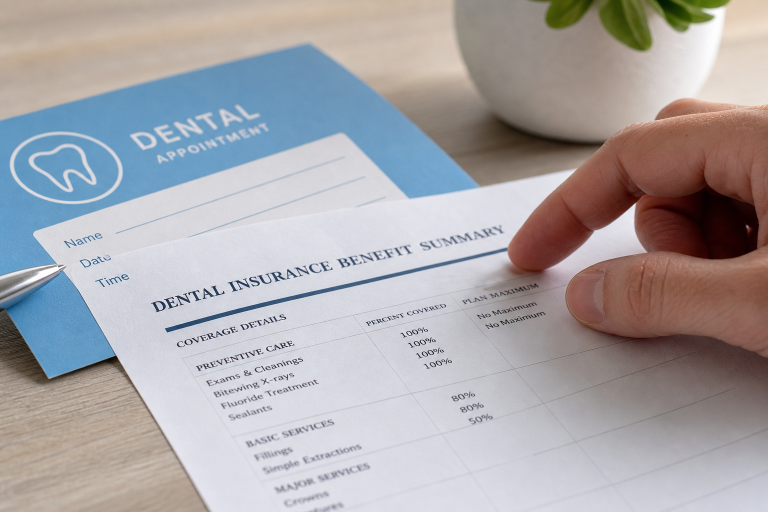
Dental benefits often divide services into categories, such as preventive, basic, and major care. A routine exam may have different plan rules than a filling or crown. A benefit percentage also does not automatically show the final amount you will pay, because the result can depend on deductibles, the plan’s allowed amount, available annual benefits, and whether the office is in network.
For example, a cleaning may be covered under preventive benefits, while a crown may be subject to a deductible or a lower coverage percentage. General descriptions are helpful, but your plan booklet, member portal, or benefits administrator provides the rules that apply to you.
Start With the Core Parts of Your Plan
Before making an appointment, locate these details in your plan materials. A plain-language overview of common dental plan designs can also help you understand how dental insurance may reduce out-of-pocket costs for covered care.
- Premium: The recurring amount paid to keep coverage active, if applicable.
- Deductible: The amount you may need to pay before certain plan benefits apply.
- Copayment: A fixed charge for a covered visit or procedure under some plans.
- Coinsurance: The portion of an allowed charge you may pay after plan rules are applied.
- Annual maximum: The most the plan will generally pay during a benefit period.
- Covered services and limits: The procedures included, excluded, or limited by frequency or age.
- Plan year: The benefit period, which may not match the calendar year.
Learn the Difference Between Common Cost Terms
- Premium: Think of this as the cost of maintaining the plan. Ask how much is paid each month or pay period.
- Deductible: This is a set amount that may be your responsibility before the plan begins contributing to certain services. Ask whether preventive care is exempt.
- Copayment: This is a stated dollar amount, rather than a percentage. Ask whether it changes by procedure.
- Coinsurance: This is usually expressed as a percentage. Ask which percentage applies to basic and major services.
- Annual maximum: This limits the plan’s payments, not necessarily your total spending. Ask when the benefit period resets and how much remains.
Check the Network Before Booking Care
An in-network dentist generally has a contracted fee arrangement with the plan. That arrangement can reduce the amount used to calculate your share of covered care. Network participation can change, so confirm it shortly before the appointment, even if you have visited the office previously.
Ask whether the treating dentist and any specialist involved are in the network. If you choose an out-of-network office, the plan may pay less, apply different rules, or provide no out-of-network benefit. You may also be responsible for the difference between the office’s charge and the amount recognized by the plan.
Compare Preventive, Basic, and Major Services
- Preventive care: Often includes exams, cleanings, and certain X-rays. Plans may impose frequency limits.
- Basic care: May include fillings, simple extractions, and some repairs.
- Major care: May include crowns, bridges, dentures, and other complex restorative procedures.
These labels are not universal. The specific plan determines a procedure’s category, coverage percentage, and eligibility requirements, so verify the procedure code and benefit rule instead of assuming a service will be paid at a particular level.
Use a Treatment Estimate Before Major Work
For a crown, root canal, implant, orthodontic treatment, or other higher-cost procedure, ask the dental office for a written treatment estimate. It may list the planned procedures, provider fees, anticipated plan payment, and estimated patient responsibility.
An estimate is a planning tool, not a final guarantee. The final amount can change if treatment changes, a claim requires additional information, benefits were used elsewhere, or a limitation applies. Ask about remaining annual maximum, frequency limits, alternatives, and services that may be excluded.
Read an Explanation of Benefits Carefully
An EOB is a claim-processing notice, not necessarily a bill. The American Dental Association explains that an Explanation of Benefits can show the allowed amount, plan payment, deductible, and patient responsibility. Compare it with the office statement after the claim is processed.
- Match the date of service and procedure description to your receipt.
- Review the allowed or negotiated amount when shown.
- Check the amount paid by the plan and any amount applied to your deductible.
- Look for remarks explaining a denial, limitation, or request for information.
- Compare the patient responsibility on the EOB with the provider’s final bill.
Know When to Ask for More Information
Request clarification when the estimate, EOB, and office statement do not appear to match. The dental office can explain planned procedures and submitted claims. Your plan administrator can explain benefit rules, claim decisions, network status, and available review or appeal processes. Save copies of all written estimates, notices, and messages.
Common Questions About Dental Benefits
Does a treatment estimate guarantee the final price?
No. It is an estimate based on information available before the claim is finalized. Changes in treatment or benefit eligibility can affect the final balance.
Does reaching the annual maximum mean I have no more costs?
No. An annual maximum generally limits what the plan pays during its benefit period. You may still owe charges for treatment after that limit is reached.
Can I use an out-of-network dentist?
Some plans allow it, while others limit or exclude out-of-network benefits. Review your plan rules before treatment.
A Simple Five-Step Review Before an Appointment
- Review your current benefit summary and plan-year dates.
- Confirm that the dentist and any specialists are in network.
- Ask which procedures are planned and how they may be billed.
- Request a written estimate for care beyond routine visits.
- Compare the final statement with the EOB and ask questions promptly.
Conclusion
Dental benefits become easier to manage when you check the network, understand the core cost terms, and request details before treatment begins. Read the plan documents, ask direct questions, keep your paperwork, and use the EOB to understand how the claim was handled. Those habits can help make dental costs more predictable and care decisions more confident.

